-
Municipal bond insurers wrapped $28.921 billion in the first three quarters 2024, a 26.8% increase from the $22.814 billion insured in the first three quarters of 2023, according to LSEG data.
 October 11

-
September volume came in over $44 billion leading volume year-to-date to hit more than $380 billion, just shy of 2023's full-year total issuance.
September 30
-
Issuance as of Wednesday is at $345.327 billion, a 32.7% increase over 2023. The Bond Buyer 30-day visible calendar on Monday was at $20.02 billion, the largest in nearly four years.
September 11
-
Municipal supply continues to grow as Bond Buyer 30-day visible supply sits at $20.02 billion and the municipal market will see one of the largest weeks of new-issuance at an estimated $13.35 billion, led by three billion-plus deals from Washington, D.C. ($1.6 billion), the New York City Transitional Finance Authority ($1.5 billion) and Illinois ($1 billion).
 September 6

-
August's volume reached $49.174 billion in 873 issues, up 25% from 2023. August's total is above the 10-year average of $40.828 billion and is also the highest monthly total this year.
August 30
-
The calendar next week largely continues "the elevated pace of primary market volume seen since May, against a backdrop of broadly supportive fund flows (LSEG inflows for eight consecutive weeks), somewhat better dealer positions (although still heavy), mid-August reinvestment to spend, but lighter late summer attendance," said J.P. Morgan strategists led by Peter DeGroot.
August 23
-
Issuers in five Far West states increased their borrowing the first half of the year, while four saw sizable decreases.
August 23
-
The region's municipal bond volume grew by 42.4%, outpacing the nationwide 32% increase in a first-half marked by gas prepay deals and Brightline's big sale.
 August 22

-
Issuers in the eight-state region sold $50.6 billion of bonds with Texas accounting for 65% of the volume.
 August 20

-
Part of the surge in issuance came from issuers tapping the capital market after several years due to the inability to no longer postpone long-delayed projects and the drying up of pandemic aid.
August 19
-
Underwriting spreads rose to $7.11 in the first half of 2024 from $3.70 in the first half of 2023.
August 15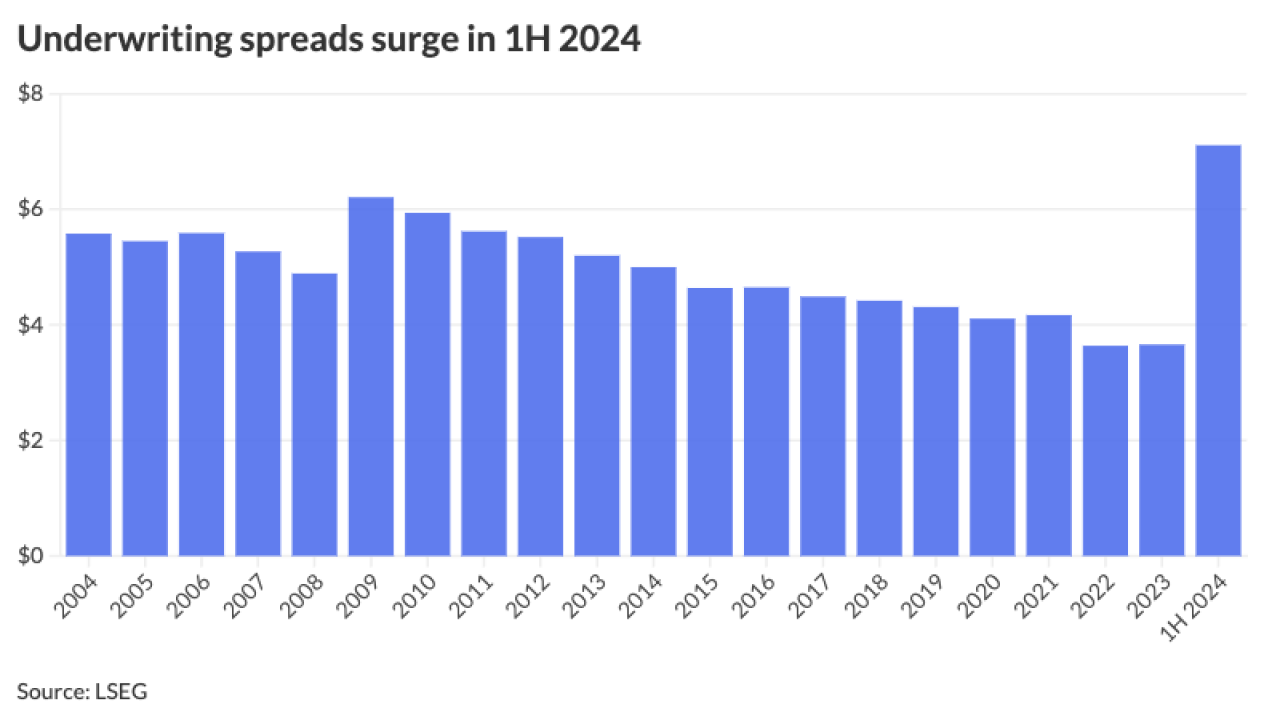
-
Data shows the average bids per competitive sale is up noticeably over the past few quarters, Justin Marlowe said, rising to 8.5 bids in Q1 2024 from 6.1 bids in Q1 2022.
August 5
-
Issuance was lumpy in July, with three weeks of $10 billion issuance sandwiched between lower issuance due to the Fourth of July holiday at the start of the month and the FOMC meeting the last week.
July 31
-
In a week that culminated in headline-grabbing events — a presidential debate, several Supreme Court decisions, more macroeconomic data to add to Fed policy expectations — municipals closed on a quiet note and in the black for June.
June 28
-
In the first half of 2024, winding-down federal aid, a resurgence of Build America Bond refundings and election uncertainty have contributed to the surge in issuance, said James Welch, a portfolio manager at Principal Asset Management.
June 28
-
Total volume currently stands at $224.13 billion, up 38.5% from $161.848 billion at this time last year. As the end of the first half approaches, several firms are revisiting their supply projections for the year, given the growth so far this year.
June 25
-
While particpants expect some pressure in the near-term with more than $16 billion on tap, they also say the current yield and ratio levels offer investors opportunity.
May 31
-
May volume "surprised on the high end and it has been one of the fastest starts to the year historically," said James Pruskowski, chief investment officer at 16Rock Asset Management.
May 31
-
"For each May dating to 2021, the average 30-year MMD was 2.74% — or 122 basis points below the current yield," FHN Financial's Kim Olsan said. "The recent adjustment offers better investor value."
May 24
-
A supply surge hits the market as The Bond Buyer 30-day visible bond volume ticks in at $17.67 billion, $10 billion of which will come the first full week of May, just as macroeconomic data moves all markets to rally.
May 3


